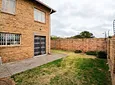
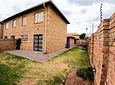
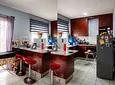
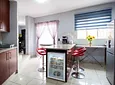
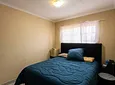

Property description
Investment calculation
Purchase price: R990,000
Rental income: R10,500 per month
Calculation Amount
Annual rental income R126,000
Annual levies (R1,400 × 12) -R16,800
Annual rates & taxes (R600 × 12) -R7,200
Net operating income R102,000 p.a.
Net monthly income before other costs R8,500
Gross rental yield 12.73%
Cap rate / net yield 10.30%
The gross yield is calculated as annual rent ÷ purchase price, while the cap rate uses the property's net operating income after operating expenses.
S
SA Property Tools
+1
Important: the 10.30% cap rate is before vacancy, maintenance, insurance, management fees, income tax and financing/bond costs. So it is a property-level cap rate, not necessarily the investor's final cash-on-cash return. SARS confirms that rental-related expenses such as rates, levies, insurance, qualifying repairs and agent fees can generally be deductible when determining taxable rental income.
S
South African Revenue Service
Capital-growth story
There is also a capital-growth component to the investment. Statistics South Africa reported 3.8% annual residential property price growth in the City of Tshwane in April 2026, while national residential property inflation was 7.9%.
S
Statistics South Africa
Annlin-specific listing data is more bullish: one current dataset reports average property values up 30.6% year-on-year, although this is listing/market data rather than a verified deeds-based capital-growth index, so I would not promise 30.6% future growth to an investor.
T
Trovit Homes
For an investment presentation, I'd therefore use 3–5% annual capital growth as a reasonable illustrative assumption, rather than relying on the exceptional 30.6% figure.
At 4% capital growth, for example:
R990,000 × 4% = R39,600 estimated annual capital appreciation
Net rental income = R102,000
Combined illustrative annual benefit = R141,600
This represents approximately 14.3% on the R990,000 purchase price, before tax, vacancy, maintenance, financing and transaction costs.
- Garden
Location rating
Nearby Transport
Nearby Education
Nearby Other
Request property details from Mems Properties
Terms of useGet in Touch

Agents
Repayment Costs
Monthly Total

Mortgage
Purchase price
Deposit 10%
RPayment term
20 yearsInterest rate
11.5%Your payment
R / mo.